Portfolio Overlap Calculator
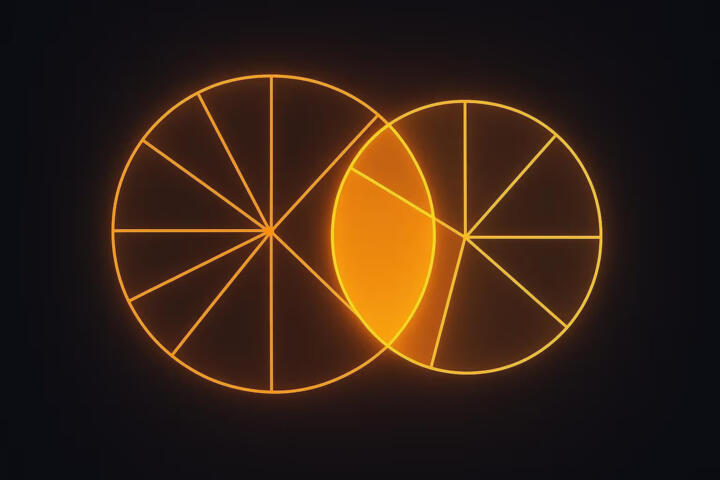
A portfolio overlap calculator measures how much two exchange-traded funds (ETFs) hold the same underlying securities, and how strongly those shared holdings contribute to each fund’s weight. The output can be expressed as a percentage of shared holdings by weight, a similarity score, or a “duplicate exposure” estimate. For example, if Fund A and Fund B both hold the same top 10 stocks, overlap can still differ widely when one fund concentrates heavily in those names while the other spreads exposure across many positions. Most calculators rely on holdings files published by the ETF provider, then align tickers and weights before computing overlap.
Overlap is not the same as correlation. Two ETFs can show high overlap in holdings yet behave differently because of sector tilts, cash positions, derivatives, or different rebalancing schedules. Conversely, two ETFs can show low overlap in listed holdings but still move together through common factor exposures such as large-cap growth or credit risk. A careful overlap calculator therefore treats holdings overlap as one input, not the whole decision.
In practice, you’ll see overlap questions come up when investors add a second ETF to “diversify,” then later notice the new fund largely repeats the same names. I’ve seen this happen with broad equity ETFs that both track similar indexes, where the holdings list looks different due to timing, but the economic exposure overlaps. The calculator helps you quantify that repetition before you commit more capital.
Main Problems And Pain Points
People often treat “same ticker” as “same exposure,” then miss the details that distort overlap. A holdings file might list a security under a different ticker, a different share class, or a temporary identifier used during corporate actions. Even when tickers match, weights can reflect stale data because holdings are typically published on a schedule that may lag the trading day. Some ETFs also use derivatives, and their published holdings may not fully represent the fund’s total market exposure.
Another common mistake involves mixing measurement definitions. One calculator might compute overlap as the sum of minimum weights for shared tickers, while another might compute overlap as the fraction of shared tickers by count. Those two approaches can disagree sharply for funds with different concentration levels. A third approach uses a similarity metric such as cosine similarity on weight vectors, which produces a score that behaves differently than “shared weight.” If you compare results across tools without checking the definition, you can reach the wrong conclusion.
Supporting technologies matter because the calculator’s accuracy depends on data alignment. Holdings data usually comes from ETF provider “holdings” or “portfolio composition” files, sometimes in CSV or XML formats. The calculator then needs a mapping layer to normalize tickers, handle ADRs and local listings, and decide how to treat cash, ETFs-of-ETFs, and derivatives. When the mapping layer is sloppy, overlap can look artificially low or high, and the error can persist quietly.
Finally, overlap can hide concentration risk. Two ETFs may share many holdings, but the shared names might sit at very different weights. If the shared names are concentrated in one fund, the overlap score might look moderate while the investor’s combined portfolio becomes heavily tilted. That’s why a calculator should show both “shared weight” and “combined exposure” for the overlapping names.
Solutions And Advice
Start With Clear Inputs
Use holdings snapshots from the same effective date when possible, or at least from the closest available dates. If Fund A’s holdings file is dated 2026-08-30 and Fund B’s is dated 2026-08-29, you should treat the overlap as an estimate rather than a precise measurement. Many providers publish daily or near-daily holdings for some products, while others publish less frequently; check the file’s “as of” date and the frequency stated by the provider. I often see investors download the first file they find, then compare it to a different date without noticing.
Decide how you will treat non-equity positions. For example, should you include cash, futures, options, or fund-of-funds holdings? A practical approach for an overlap calculator focused on equity concentration is to include only common stocks and ETFs-of-ETFs if you can map them to their underlying holdings. If you include derivatives as tickers, you may get misleading overlap because derivatives represent exposure to an index or sector rather than a specific issuer.
Pick A Consistent Overlap Metric
Choose a metric that matches your question. If you want “how much of each fund’s weight is duplicated,” a shared-weight approach works well: for each shared security, take the smaller of the two weights, then sum across shared securities. This yields a number that behaves like “overlap by weight,” bounded by each fund’s total weight. If you want “how similar are the portfolios,” a cosine similarity on normalized weights can help, but it produces a score that does not translate directly into “duplicate dollars.”
For decision support, also compute the top overlapping names by combined weight. A mild frustration here is that many calculators show only one overlap percentage and hide the underlying list, which prevents you from checking whether the overlap comes from a few concentrated names or broad repetition across many holdings.
Sanity-Check With Sector And Factor Tilt
After you compute overlap, compare it to sector and style exposures from the ETF provider or a reputable data vendor. If two ETFs show low holdings overlap but both report similar sector weights and similar factor tilts, the overlap calculator may miss shared risk carried through derivatives or index methodology. If two ETFs show high holdings overlap but different sector tilts, the difference often comes from weight timing, corporate actions, or how the provider classifies holdings.
Use a small test portfolio to interpret results. For instance, if you plan to hold 50% of each ETF, you can compute combined exposure for the overlapping names by multiplying each ETF’s weight by your allocation. That turns overlap from an abstract score into a “what you actually own” view.
Track Data Freshness And Rebalance Effects
Holdings overlap changes when ETFs rebalance, when index constituents change, or when corporate actions occur. A calculator should record the holdings file date and the source. If you rerun the calculation monthly, you can observe whether overlap is stable or drifting. Some ETFs rebalance infrequently, while others track indexes with frequent constituent changes; the overlap calculator should reflect that reality rather than pretending the holdings list is static.
If you use a third-party tool, verify whether it updates holdings daily and whether it uses the same share-class mapping rules across ETFs. A mismatch in mapping rules can create a “phantom overlap” effect where the same economic exposure appears under different identifiers.
Case Examples
Two Broad Equity ETFs
An investor holds ETF A and considers adding ETF B. The overlap calculator uses shared-weight overlap on the latest holdings files dated 2026-07-31 for both funds. The result shows moderate overlap by weight, but the top overlapping names account for most of the shared weight. When the investor computes combined exposure for those names, the combined portfolio becomes concentrated in a handful of mega-cap stocks, even though the overlap percentage alone looked less alarming. The investor decides to size the new ETF smaller and adds a different sleeve with lower overlap rather than assuming “broad” means “non-overlapping.”
Adding A Thematic ETF
A second investor adds a thematic ETF focused on cloud infrastructure. The overlap calculator shows low overlap by weight with a broad market ETF, yet the thematic ETF’s holdings overlap heavily in a few sectors such as software and semiconductors. The investor then checks sector tilts and finds the thematic ETF increases exposure to the same factor drivers that already exist in the broad ETF. The overlap calculator alone does not capture factor overlap, so the investor uses the overlap list to confirm that the thematic fund’s “new” exposure comes from a narrower set of issuers rather than a different risk profile.
Comparison Table And Checklist
| Method | What It Measures | Strength | Limitation |
|---|---|---|---|
| Shared Weight (Min Weights) | Sum of min(weightA, weightB) for shared tickers | Directly interpretable as duplicated weight | Sensitive to ticker mapping and holdings date |
| Shared Ticker Count | Fraction of tickers appearing in both portfolios | Simple to compute and explain | Ignores concentration and weight differences |
| Cosine Similarity | Similarity of weight vectors after normalization | Captures shape of the weight distribution | Harder to translate into “duplicate dollars” |
Checklist for using an overlap calculator you trust:
- Confirm the holdings file “as of” date for each ETF and record it in your notes.
- Verify the calculator’s ticker normalization rules (share classes, ADRs, corporate action handling).
- Check which positions are included (cash, ETFs-of-ETFs, derivatives) and whether the tool documents that choice.
- Use one metric consistently across comparisons, then interpret it with the overlapping-name list.
- Compute combined exposure for your intended allocations, not just overlap between two funds.
- Re-run after major index changes or at a fixed cadence (monthly or quarterly) to detect drift.
Common Mistakes
One mistake involves comparing overlap results across tools without reading the metric definition. A shared-weight score and a shared-ticker-count score can both be called “overlap,” yet they answer different questions. Another mistake involves ignoring the holdings date and assuming the latest file reflects current exposure; for many ETFs, holdings can change between publication dates.
Some investors also treat an overlap list as a complete picture of risk. If an ETF holds futures or options, the economic exposure may not appear as a direct issuer weight in the holdings file. In those cases, a holdings-based overlap calculator can understate shared risk. A second risk is overconfidence: a high overlap score does not guarantee identical performance because index methodology, rebalancing timing, and cash management can still differ.
Finally, people sometimes forget that ETF holdings can include multiple share classes of the same company. If the mapping layer treats them as different tickers, overlap can look lower than reality. I’ve seen this happen when one fund lists a primary listing while another lists an alternate listing, and the calculator treats them as unrelated symbols.
FAQ
What Is Portfolio Overlap?
Portfolio overlap measures how much two ETFs share the same underlying holdings and how much those shared holdings contribute to each fund’s weight, based on a defined metric and a specific holdings snapshot date.
Which Overlap Metric Should I Use?
Use shared-weight (sum of min weights) when you want duplicated exposure by weight. Use shared-ticker count when you want overlap by presence, and use cosine similarity when you want similarity of the weight distribution shape.
How Do I Handle Different Holdings Dates?
Use the closest available “as of” dates and treat the result as an estimate. Record the dates so you can rerun the calculation when you want a more current comparison.
Do Derivatives Affect Overlap Calculations?
Holdings-based overlap calculators often reflect listed issuer weights and may not capture derivative exposure fully. Check whether the tool includes derivatives and how it maps them to underlying risk.
Why Do Two ETFs With Similar Indexes Still Show Low Overlap?
Low overlap can come from ticker mapping differences, corporate action timing, different inclusion rules for cash or non-equity positions, or holdings publication timing that lags the trading day.
Author's Insight
Portfolio overlap calculators work best when you treat them as a data-alignment and metric-definition exercise, not a single magic percentage. The most common failure mode comes from mismatched holdings dates and inconsistent ticker normalization, which can quietly distort overlap. A practical workflow records the holdings “as of” dates, lists the top overlapping names, and converts overlap into combined exposure for your intended allocations. If you want to compare results across tools, you should verify the metric definition and included position types, then rerun with the same inputs.
Key Takeaways
- Overlap calculators quantify shared holdings under a specific metric and a specific holdings snapshot date.
- Shared-weight overlap helps estimate duplicated exposure by weight, while ticker-count overlap ignores concentration.
- Ticker mapping, holdings freshness, and inclusion of cash or derivatives can materially change results.
- Use the overlapping-name list and compute combined exposure for your planned allocations to interpret the score.
- Re-run periodically to detect drift from rebalancing and index changes.